Local Real Estate News, Market Trends & Homeowner Tips

Tired of confusing national headlines? Get the real truth about the Sacramento housing market right here! Our blog is updated regularly with boots-on-the-ground local news, shifting real estate trends, and insider tips you actually need. Whether you are tracking mortgage rates, hunting for hidden gems in Elk Grove, or preparing to sell for top dollar, I’ve got you covered. Bookmark this page to stay ahead of the competition!

Aug. 27, 2025

Don't Make This Major Mistake When Buying New Construction

Mistakes to avoid when buying a new construction home without a real estate agent

The Biggest Mistake When Buying New Construction (And How to Avoid It)

The attraction of a brand-new home is incredibly powerful: a completely clean slate, modern energy-efficient architecture, up-to-date color palettes, and everything functioning perfectly from day one. New construction communities are booming throughout the Greater Sacramento region, offering beautiful opportunities to design a property tailored specifically to your lifestyle.

But as you cross the threshold of a stunningly staged model home, there is one critical mistake that countless buyers make—a single misstep that can easily cost them thousands of dollars in lost concessions and valuable peace of mind: touring and registering with the community without their own independent real estate agent.

It is easy to fall into the mindset of thinking: "Why do I even need an outside agent? The salesperson sitting in the model office is incredibly friendly and helpful!" This is the single biggest misconception in the new-build arena. That accommodating representative in the sales office works exclusively for the builder's corporate entity, not for you. Their fiduciary duty is to maximize the builder's profit margin and protect the builder's interests—objectives that are often in direct conflict with your own as a buyer.

To level the playing field, you need a dedicated professional working on your side of the table from your very first visit.


The Representation Breakdown: Who Represents Whom?

  • The Builder’s Sales Representative: They are highly specialized experts on their specific inventory. They know the exact floor plans, lot premiums, design center upgrade packages, and community association rules inside and out. They are there to guide you smoothly through the builder's custom purchase agreement, but their ultimate performance is judged by how high a price and how favorable the terms they secure for the developer.
  • Your Independent Real Estate Agent: Your agent works entirely and exclusively for you. They function as your strategic advocate, legal buffer, and lead negotiator. Their sole objective is to safeguard your financial health, uncover hidden leverage, and manage the complex multi-month construction timeline on your behalf.

The Distinct Benefits of Independent Representation on a New Build

Navigating a raw dirt-to-turnkey transaction alongside an experienced Sacramento real estate advocate provides a massive list of protections:

  • Unlocking Expert Negotiation Concessions: While production builders rarely lower the base sticker price of a home (as doing so hurts the appraised value of future phases), they have substantial flexibility elsewhere. An experienced agent knows how to skillfully negotiate for substantial structural upgrades, premium appliance packages, lot premium waivers, or closing cost credits. They can also cross-compare financing incentives, like temporary interest rate buy-downs offered by the builder's in-house lender versus independent mortgage brokers.
  • Deconstructing the Builder's Contract: Standard builder purchase contracts are completely different from traditional state-approved residential agreements. They are custom-drafted corporate legal documents heavily biased toward the builder. These files often include complex clauses regarding open-ended construction delays, material cost increases passed to the buyer, and restrictive warranty frameworks. Your agent is trained to spot these financial pitfalls before you authorize the paperwork.
  • A Neutral Third-Party Advocate: Building a home from the ground up takes months, and communication boundaries can break down. If construction timelines slip unexpectedly, a finish is installed incorrectly, or disputes arise regarding design selections, your agent serves as your official point of contact. They hold the builder strictly accountable to the written parameters of your contract.
  • Coordinating Independent Home Inspections: Never skip a comprehensive home inspection just because a property is brand new! Municipal building inspectors only verify minimum structural code compliance—they do not inspect for fit, finish, or architectural craftsmanship. Your agent will coordinate an independent inspector to conduct a pre-drywall inspection (verifying framing, plumbing rough-ins, and electrical pathways before the walls are sealed) and a comprehensive final inspection prior to your official walkthrough.
  • Objective Local Market Mapping: An on-site representative is only authorized to sell you on their specific subdivision. Your personal agent possesses a birds-eye view of the entire local market. They provide an objective comparison of how that specific new build comapres against competing developments or high-end resale properties in neighboring communities, ensuring you pay true fair-market value.

⚠️ The Golden Rule of New Construction Staging: If you plan to tour any new construction community, you must bring your real estate agent with you on your absolute first physical visit, or clearly register them at the guest sign-in desk. The vast majority of builders enforce a strict procurement policy: if you cross their threshold alone, they will refuse to recognize or compensate any outside agent later in the process. This effectively strips you of your right to free professional representation.

Frequently Asked Questions About New Builds

Does hiring a real estate agent cost me more when buying new construction?

No. The compensation for your real estate agent is entirely covered by the builder via a pre-allocated corporate marketing and sales budget. Builders do not offer lower prices to unrepresented buyers who walk in alone; they simply retain that extra profit for themselves while you lose out on professional protection.

Can I use my own lender when purchasing a brand-new home?

Yes. While builders frequently offer attractive financial incentives or design center credits if you use their "preferred" in-house mortgage company, you always maintain the legal right to shop around. Your agent will help you run a side-by-side financial analysis to determine if the builder's incentive package actually beats out an independent loan structure over the long term.


Partner With a Trusted Advocate for Your New Build Journey

Building a brand-new home is an incredibly rewarding milestone. Watching your design choices transform from a blue-lined blueprint into a physical structure is unmatched. However, keeping the process stress-free and financially sound requires having the right professional team stationed firmly in your corner.

Planning to explore the newest master-planned developments across Sacramento? Do not walk into the sales offices unprotected. Connect with our team today before you start touring, and let us ensure you secure the absolute best pricing, upgrades, and contractual terms possible on your dream home!
Posted in Buyer Tips
Aug. 22, 2025

Sacramento Housing Market: Is the Tide Turning? July 2025 Update

sacramento real estate market, sacramento housing market, sacramento market update, sacramento real estate trends july 2025, sacramento real estate, sacramento homes for sale, sacramento home prices, average home price sacramento, sell my home sacramento, what is my home worth sacramento?, best time to sell in sacramento, how to sell my house fast sacramento, home value sacramento

Are you wondering what's happening with Sacramento homes for sale? The Sacramento real estate market is still a hot topic, and July 2025 brought some interesting changes. If you're thinking of buying a home in Sacramento or wondering how to sell your home in Sacramento, this simple guide will help you understand the latest trends and what they mean for you. Let's break down the key numbers!

July 2025 Sacramento Housing Market: The Main Points

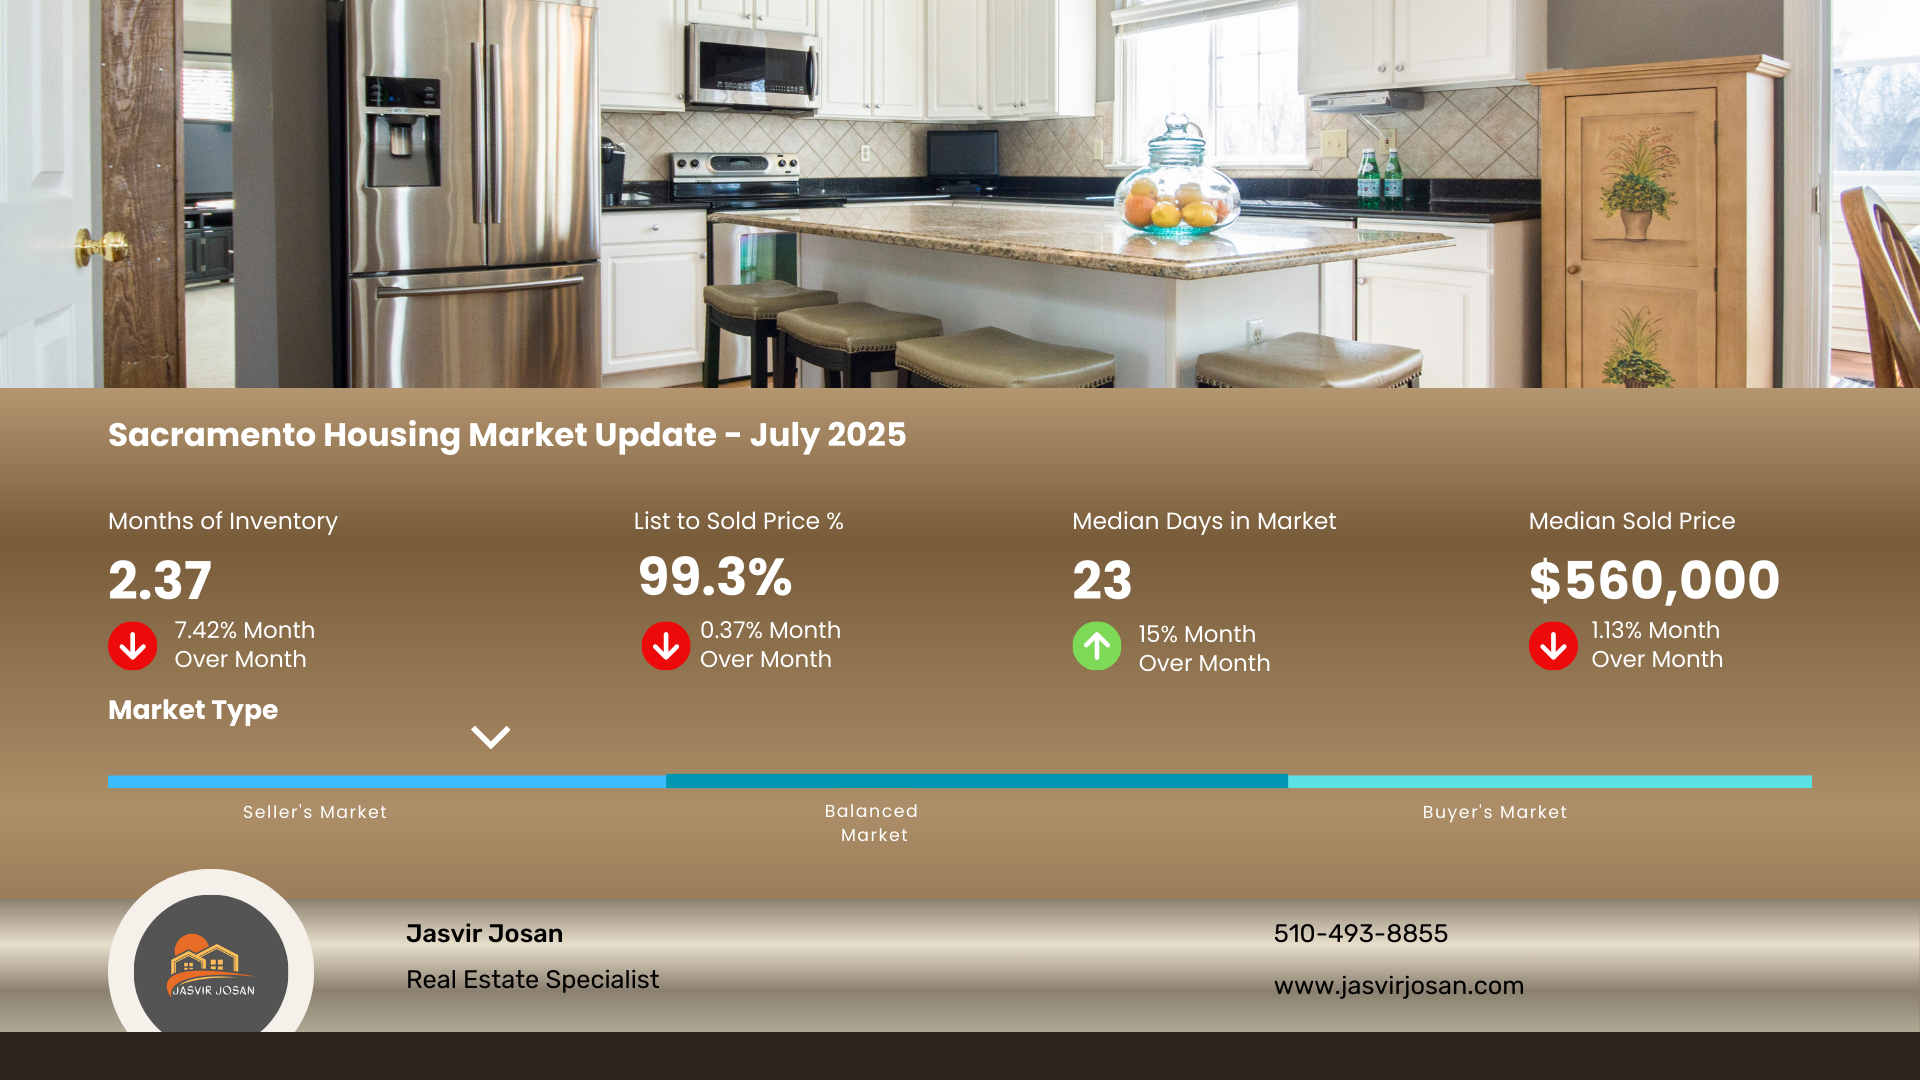
  • Months of Inventory: 2.37 (Down 7.42% from last month). 
    • What this means: There are fewer homes for sale this month. This still gives sellers the advantage.
  • List to Sold Price %: 99.3% (Down 0.37% from last month)
    • What this means: Homes are still selling very close to their asking price. Buyers are still willing to pay what sellers are asking.
  • Median Days in Market: 23 (Up 15% from last month)
    • What this means: Important change! Homes are taking a bit longer to sell. This gives buyers a little more time to make a decision.
  • Median Sold Price: $560,000 (Down 1.13% from last month)
    • What this means: The average price of homes sold has dropped slightly. This could be a sign of the market balancing out.

What These Numbers Mean for You

The Sacramento real estate market is still a seller's market, but it's not as fast-paced as it was. The slight dip in prices and the increase in time on the market could be good news for buyers.

  • For Buyers: You might have a bit more time to find your perfect home and could see less intense competition.
  • For Sellers: It's still a great time to sell, but pricing your home correctly and making it look its best is key to getting a quick sale.

Ready to Make Your Move?

The Sacramento real estate market can be tricky to navigate on your own. I'm here to help you understand these trends and make the best decision for your family. Whether you want to buy a home in Sacramento or sell a house in Sacramento, let's talk about your goals!

Posted in Market Updates
Aug. 13, 2025

Who Are the Important People on Your Side in Real Estate

The essential professional team required for a successful real estate transaction

You have officially made the choice to buy or sell a home in the Greater Sacramento region—that is a monumental decision and an incredibly exciting milestone! As you begin this journey, you will quickly realize that navigating a modern property transaction is never a solo mission. A truly successful, legally sound real estate closing is a highly coordinated team effort. Surrounding yourself with the right professionals is the ultimate key to a smooth, protected, and stress-free experience.

Think of your real estate transaction team as your personal council of guides, each with a specific, highly technical area of expertise to guide you safely through the escrow process. Their combined objective is to completely protect your financial interests, insulate you from legal liability, manage complex logistical timelines, and ultimately help you achieve your homeownership goals.

Here is your detailed introduction to the important people standing on your side of the table in a real estate transaction and exactly what they achieve for you.


The Real Estate Core Team at a Glance

Team Member Primary Focus Key Benefit to You
Real Estate Agent Strategic project manager & lead negotiator Protects your overall equity, targets listings, and drafts legal terms.
Mortgage Lender Financial structural underwriting Secures loan funding, optimizes interest rates, and issues pre-approvals.
Home Inspector Physical and structural evaluation Uncovers hidden material defects and provides repair leverage.
Home Appraiser Independent third-party asset valuation Ensures the property's actual worth justifies the underlying mortgage contract.
Title & Escrow Officer Neutral funds management & deed recording Guarantees clean title transfer and safely holding earnest money deposits.

1. Your Real Estate Agent: The Field Quarterback

This is your primary baseline point of contact, your strategic advisor, and your contract advocate. A premier real estate agent is far more than a simple transaction salesperson—they are local market economists, defensive contract writers, and logistical coordinators rolled into a single representative.

  • For Home Buyers: Your agent works closely with you to isolate your lifestyle needs, search for qualified inventory, arrange private property viewings, and creates competitive purchase offers. They utilize hyper-local insight regarding specific Sacramento neighborhoods to help you discover the ideal fit while steering you away from over-priced listings.
  • For Home Sellers: Your agent generates highly accurate, real-time comparative market analyses to establish a pricing strategy that maximizes your final net proceeds. They coordinate high-end digital marketing campaigns, screen incoming buyer profiles, and seamlessly negotiate multi-offer scenarios to secure your preferred terms.

2. Your Mortgage Lender: The Financial Architect

Your mortgage lender is the financial expert who structures and secures the capital required for your residential property purchase. Aligning with an incredibly responsive, highly reputable lender is a critical initial milestone that should take place long before stepping inside an open house.

  • The Power of True Pre-Approval: A skilled loan officer will navigate you through a formal mortgage pre-approval process, analyzing your tax returns, credit scores, and asset portfolios. Walking into a transaction with an official pre-approval letter signals to sellers that your financial profile is fully verified and stable.
  • Tailoring Your Debt Profile: They will break down different, highly complex loan structures to determine the absolute cleanest fit for your specific lifestyle, tracking various programs including conventional, FHA, or specialized VA loans.
  • Clearing the Underwriting Milestone: Once a purchase agreement is ratified by both parties, your lender works tirelessly behind the scenes to verify files, clear conditions, and issue the final "clear to close."

3. The Home Inspector: Your Objective Eyes and Ears

For buyers, skipping a professional home inspection is a catastrophic financial risk. An inspector's core duty is to provide an entirely objective, incredibly deep, and unbiased forensic evaluation of a property's current physical health.

  • The Structural Blueprint Review: A licensed inspector will carefully examine the home's primary systems, including the roof, concrete foundation stability, HVAC functionality, electrical wiring panels, and primary plumbing mainlines. They package their findings into a clear, detailed photographic report outlining everything from minor cosmetic touch-ups to severe structural failure.
  • Unlocking Financial Counter-Leverage: The comprehensive data provided inside an inspection report serves as your ultimate negotiating chip. It empowers your agent to safely demand targeted seller repairs, structure substantial price drops, request closing cost credits, or walk away entirely with your deposit fully intact if the physical defects are too extensive.
  • Local Deficiencies Competency: Top-tier local inspectors understand specific regional nuances, such as typical foundation settlement patterns caused by local clay soils or specific wood-destroying pest vulnerabilities common to older valley builds.
Pro-Tip for Transactions: The home inspector evaluates the condition of the house, whereas the appraiser evaluates the value of the house. Both are critical protection checkpoints, but they serve completely different purposes.

4. The Home Appraiser: The Independent Valuator

The home appraiser is a completely independent, neutral third-party professional retained by the lending institution. Their responsibility is to deliver a completely unbiased valuation of the real estate's fair market value.

  • Insulating the Financial Investment: Banks are legally restricted from lending more money than a physical asset is worth. The formal appraisal ensures the underlying home value cleanly justifies the mortgage loan amount, protecting the bank's security position and keeping you from overpaying.
  • Data-Driven Calculations: Appraisers rely heavily on highly standardized criteria, comparing recent closed neighborhood sales (comps), current structural square footage, lot location dynamics, and visible upgrades. The final value calculation must land at or above the agreed contract price for financing to remain on schedule.

5. The Title & Escrow Officer: The Neutral Security Safe

In the state of California, your escrow officer operates as an entirely neutral, non-biased intermediary who securely holds all institutional funds, earnest money deposits, and legal instruments associated with the transfer of ownership.

  • Safeguarding Earnest Deposits: The escrow officer maintains your sensitive financial deposits inside an independent, secure escrow account. No capital moves without strict, mutually signed authorizations matching both the buyer and seller instructions.
  • Managing Title Security & Official Recording: Simultaneously, the title department conducts extensive historical title searches to guarantee the seller has the clean legal right to transfer the home, ensuring the property is free of hidden mechanics liens, tax judgments, or boundary disputes. Once everything aligns perfectly, the escrow officer orchestrates the distribution of funds and registers the new deed directly with the county recorder's office.

Frequently Asked Questions About Real Estate Teams

Can I choose my own title and escrow company?

Yes. In a standard California purchase contract, the choice of the title and escrow provider is completely open to negotiation between the buyer and the seller. Typically, local customs or specific negotiations dictate which premier firm is written into the final agreement to manage the closing timeline.

How do I know if the professionals I hire are reputable?

The safest strategy is to rely on your real estate agent's vetted professional network. Experienced local agents close dozens of transactions a year and maintain pre-screened relationships with the most thorough inspectors, reliable loan officers, and efficient escrow managers in the region.


Your Dream Team is Ready to Secure Your Success

Navigating the active, fast-paced Sacramento real estate landscape is filled with complex legal requirements, strict contractual timelines, and substantial financial weight. You should never feel forced to take on these milestones unsupported. Building a fortified team of elite, hyper-focused professionals is the single smartest decision you can make for your household's wealth.

Ready to kickstart your real estate journey alongside the best professional team in the valley? Let's connect today for a personalized, data-backed strategy session. We will connect you directly with premier local lenders, meticulous home inspectors, and elite escrow teams to guarantee your real estate transition is flawlessly managed from day one! Contact us today to get started!

July 30, 2025

What Documents Do I Need To Get Pre-Approved for a Mortgage?

Essential financial documents required for mortgage preapproval checklist

Introduction: Preparing for Your Ultimate Homebuying Power Move

It is an incredible milestone when the dream of buying a home transitions from an abstract thought into a real, actionable strategy. One of the absolute first, and most defining, steps you can take to solidify this journey is securing a formal mortgage pre-approval. This isn't just a basic administrative formality; it is a highly influential asset that proves to home sellers and listing agents that you are a serious, financially vetted buyer ready to close quickly.

But what exactly do underwriting lenders need to review when you submit your file? While the prospect of digging through historical financial archives can feel a bit daunting, the process is incredibly straightforward once you break it down by category. Getting organized ahead of time will insulate you from transactional delays and eliminate stress down the line!


The Master Pre-Approval Checklist at a Glance

Before diving into the fine details, use this quick-reference summary table to organize your digital files:

Document Category Standard W-2 Employee Requirements Self-Employed / Special Rules
1. Identity & Residence Valid Driver's License/Passport, SSN Card 2-year formal residential address history
2. Income Verification Last 30 days of pay stubs, 2 years of W-2s 2 years of corporate tax returns, YTD Profit & Loss, 1099s
3. Asset Verification 2-3 months of standard bank statements (all pages) Quarterly 401(k)/IRA portfolios, signed down payment gift letters
4. Liabilities & History Standard credit pull authorization Recent monthly statements for auto, student, or personal debt lines

Why Do Lenders Require This Volume of Paperwork?

The underlying reason is simple: Underwriters are legally tasked with verifying your "Ability to Repay" the prospective home loan. By conducting a forensic review of your historical financial footprint, they analyze your baseline income stability, your historical track record with revolving credit, and your overall liquid net worth. This verification process sets a definitive boundary for exactly how much capital they can safely lend you.


Your Comprehensive Pre-Approval Checklist

Having these exact items indexed and saved into a secure digital folder allows top-tier mortgage partners to review your file and issue a formal pre-approval letter in a matter of days.

1. Proof of Identity & Legal Residence

Lenders must verify your legal identity and establish fraud prevention protocols right out of the gate.

  • Government-Issued Photo Identification: A current, unexpired state driver's license, military ID, or federal passport.
  • Taxpayer Identification: Your physical Social Security Card or official Individual Taxpayer Identification Number (ITIN).
  • Residential Records: A complete list of your physical living addresses spanning the trailing 24 months.

2. In-Depth Income & Employment Verification

Lenders prioritize consistent, predictable revenue streams above almost everything else.

  • Recent Pay Stubs: Your most recent consecutive 30 days' worth of earnings records (showing year-to-date running totals).
  • W-2 Tax Statements: Signed W-2 forms for the past two consecutive tax years from all associated employers.
  • Federal Tax Filings: Complete, executed personal federal tax returns (Form 1040) along with all attached schedules for the past two years.
💡 Note for Self-Employed & Independent Contractors: If you operate as a business owner or 1099 contractor, prepare for enhanced underwriting. You will typically need to present two years of complete corporate tax returns (1120-S or 1065), a signed year-to-date Profit & Loss (P&L) statement, a current corporate balance sheet, and consecutive business bank statements to verify cash flow stability.

Alternative Revenue Streams: Remember to gather certified documentation if you claim bonus structures, commission splits, child support payouts, alimony, retirement pensions, or structural Social Security benefits (award letters must prove these funds will continue for at least three years).

3. Liquid Asset Documentation

Lenders must ensure you possess clean, verifiable liquid capital to cover your down payment obligations and escrow closing costs, while still maintaining emergency cash reserves.

  • Comprehensive Bank Statements: Two to three months of consecutive checking and savings statements. Crucial step: Provide every single page, including blank filler pages. Underwriters scan these looking for large, unvouched cash injections or sudden liquid drawdowns.
  • Investment & Retirement Portfolios: Your latest quarterly statements tracking 401(k) accounts, traditional or Roth IRAs, mutual funds, or individual brokerage trading platforms.
  • Down Payment Gift Letters: If a portion of your asset pool is being provided by a family member, you must supply a formalized, signed gift letter explicitly stating the funds are a non-repayable gift, accompanied by the donor's bank trail to track the source of capital.

4. Outstanding Debt & Revolving Liability Information

This category maps your Debt-to-Income (DTI) ratio, allowing lenders to see how much of your monthly income is already allocated to existing debts.

  • Authorized Credit Screening: While the lender conducts their own automated tri-merge credit pull, checking your profile beforehand ensures zero reporting surprises.
  • Installment Account Verification: Up-to-date statements for active auto loans, student financing lines, personal installment products, or revolving credit card accounts.

5. Specialized Circumstance Paperwork

  • Verified Rental History: If you are transitioning out of a rental agreement, some underwriters require proof of consistent rent payments (canceled checks or direct bank ledger transfers) alongside direct landlord contact details for the last 12 to 24 months.
  • Legal Disclosures: Certified court paperwork or divorce decrees outlining legally binding child support or alimony payment structures.
  • Historical Real Estate Records: Your current mortgage statement, active hazard insurance declarations, and property tax assessments if you currently own other real estate assets.
  • Legal Discharges: Formal discharge papers and structural explanations if your financial history includes a past bankruptcy or home foreclosure timeline.

Frequently Asked Questions About Pre-Approval Paperwork

How long is a mortgage pre-approval letter valid?

In most traditional lending frameworks, a formal pre-approval letter is active for 60 to 90 days. Because your financial documents age and credit scores update, lenders will simply require a fresh set of pay stubs and bank statements to extend the timeline if your home search carries longer.

What is the difference between pre-qualification and pre-approval?

Pre-qualification is a surface-level estimate based purely on unverified information you provide verbally. Pre-approval is a firm, formal commitment where an underwriter physically audits your tax returns, credit reports, and asset sheets, putting you in a vastly superior negotiating position.


Why Early Pre-Approval is Your Ultimate Advantage

Stepping out to begin looking at homes with an active pre-approval letter completely alters your homebuying experience. It establishes a rock-solid, non-negotiable budget boundary, validates your purchasing capability to prospective home sellers, and drastically accelerates your closing timeline once your contract is accepted.

Ready to get your financial profile perfectly organized for the active market? Organizing your paperwork is your first major step toward long-term wealth. Let's make sure it's handled flawlessly. Contact our office today! We work hand-in-hand with top-tier local mortgage lenders who will guide you through the underwriting process with maximum efficiency, positioning you to secure your perfect home safely!

Posted in Buyer Tips
July 23, 2025

5 Benefits To Owning Your Own Home in Sacramento!

The long-term financial and personal benefits of owning a home in Sacramento

For generations, homeownership has stood firmly as a cornerstone of the American dream. Here in the diverse and thriving Greater Sacramento region, that dream holds an even deeper appeal! While the journey to saving a down payment and ultimately buying a home requires a significant effort, the long-term rewards are huge—offering far more security, financial leverage, and pride than a simple rental agreement ever could.

Whether you are currently renting a property and considering making the tactical leap into the market, or you are a long-time resident reflecting on the true value of your asset, it is worth exploring the profound advantages of owning your own home. Let’s dive into the five key advantages that make real estate ownership one of the smartest and most fulfilling financial decisions you can make in Sacramento.


A Clear Comparison: Renting vs. Owning in Sacramento

To see how a property purchase reshapes your long-term balance sheet compared to a standard lease, consider this quick-reference breakdown:

Financial & Lifestyle Feature Renting a Property Owning Your Home
Wealth Accumulation Zero (100% of your capital builds your landlord's equity) High (Builds personal net worth via principal paydown & appreciation)
Payment Predictability Vulnerable to annual landlord rent increases Locked-in fixed principal and interest for 15 or 30 years
Tax Deductions None available to the tenant Substantial (Mortgage interest, property taxes, capital gains exclusions)
Creative Freedom Strict limitations on paint, updates, and pets Absolute control to remodel, landscape, and personalize

1. Building Multi-Generational Wealth Through Equity

When you write a check for rent, that capital leaves your pocket forever, working exclusively to pay off someone else's mortgage. However, when you own your home, every single monthly payment acts as a forced savings plan that directly builds your personal net worth. This process is known as capturing home equity.

  • The Mechanics of Equity: Equity represents the true dollar portion of the real estate asset that you fully own. It is calculated by taking the current market value of your property and subtracting your outstanding mortgage balance.
  • The Dual Growth Engine: Your equity compounds through two channels: as you systematically reduce your loan balance each month, and as the Sacramento housing market historically trends upward over time.
  • A Versatile Financial Safety Net: Accumulated home equity is a highly functional financial resource. Over time, it can be tapped responsibly via home equity lines of credit (HELOCs) or strategic cash-out refinances to fund home additions, launch businesses, or anchor retirement goals.

2. Capturing Significant Tax Advantages

The American tax code is inherently designed to reward and incentivize homeowners, providing key write-offs that keep more hard-earned cash inside your bank account annually.

  • The Mortgage Interest Deduction: For standard home purchases, the interest you pay on your mortgage can be deducted directly from your taxable income. This provides massive relief during the initial years of your loan term, when interest represents the largest chunk of your monthly allocation.
  • Strategic Property Tax Breaks: Sacramento homeowners can typically deduct state and local property taxes (SALT) up to federally mandated thresholds, directly optimizing end-of-year tax exposure.
  • The California Homeowners’ Exemption: If you occupy the property as your primary residence, you are eligible to file for our unique local California exemption. This lowers your home’s baseline assessed value by $7,000, creating an automatic, permanent discount on your annual property tax bill.
📋 Tax Planning Note: Tax laws contain specific nuances based on filing status and overall income profiles. To ensure you are fully maximizing your write-offs, always partner with a licensed Certified Public Accountant (CPA) to customize your filing strategy!

3. Stability and Long-Term Cost Predictability

Renting exposes you to constant housing insecurity. Landlords can adjust rents upward at the end of a lease cycle, force sudden move-outs if they choose to liquidate the asset, or price you completely out of a beloved neighborhood. Owning completely eliminates this volatility.

  • Locking in Your Budget: Securing a standard fixed-rate mortgage payment guarantees that your core principal and interest costs remain exactly the same for the entire 15- or 30-year lifecycle of the debt. This permanent predictability takes the guesswork out of household budgeting.
  • The Ultimate Inflation Shield: As inflation drives up consumer goods, services, and local rental rates across the valley, your fixed housing payment remains stable. Over a multi-year timeline, your home expenses actually become relatively more affordable in comparison to your growing earning power.

4. Complete Freedom to Personalize and Control Your Space

The non-financial, psychological rewards of owning your own land are just as powerful as the economic metrics. Your home is an authentic expression of who you are.

  • Unrestricted Customization: Want to take down an interior wall to build an open-concept living space? Eager to modern-stage your kitchen cabinets, plant an expansive backyard organic garden, or install custom hardwood floors? You hold absolute creative authority without ever waiting around for a landlord's permission.
  • Escaping Arbitrary Rules: Say goodbye forever to restrictive pet deposits, strict limits on animal weights, drilling limitations, and intrusive structural inspections. You establish the house rules.

5. Putting Down Deep Roots and Cultivating Community

Homeownership is the primary catalyst for long-term social stability, fostering deep neighborhood connections and a true sense of local belonging.

  • Hyper-Local Engagement: Because homeowners tend to remain in place much longer than transient renters, they build meaningful, lifelong relationships with neighbors. They become actively invested in supporting local schools, neighborhood safety watch initiatives, and community parks throughout established Sacramento neighborhoods.
  • Targeted Suburban Foundations: Whether you anchor your family in the top-tier school districts of Elk Grove, settle into the modern, master-planned developments of Natomas, or embrace the timeless architectural character of historic East Sacramento, owning a home provides an invaluable foundation of consistency for growing families.

Frequently Asked Questions About Local Homeownership

How long should I plan to stay in a home to ensure buying beats renting?

As a general rule of thumb in the Sacramento market, if you plan to remain in a specific geographic area for at least 3 to 5 years, buying almost always outperforms renting. This "break-even" window allows your property value to appreciate sufficiently to offset your initial closing costs while steadily building equity.

Are there local programs available for first-time buyers in Sacramento?

Yes. Buyers across Sacramento have access to excellent state and local assistance structures, including down payment grant programs through the California Housing Finance Agency (CalHFA). These initiatives make crossing the bridge from renter to homeowner much more accessible than many assume.


Ready to Start Building Your Financial Future?

Transitioning from renting to owning is an empowering lifestyle shift. It represents a conscious move away from funding someone else's retirement portfolio and toward securing your own household’s long-term financial freedom.

Curious about exploring your purchasing power in the current Sacramento market? Let’s look at the options together. Contact our office today for a private, personalized strategy consultation. I am here to guide you step-by-step through the process, ensuring you capitalize on every single wealth-building advantage homeownership has to offer!

Posted in Buyer Tips
July 17, 2025

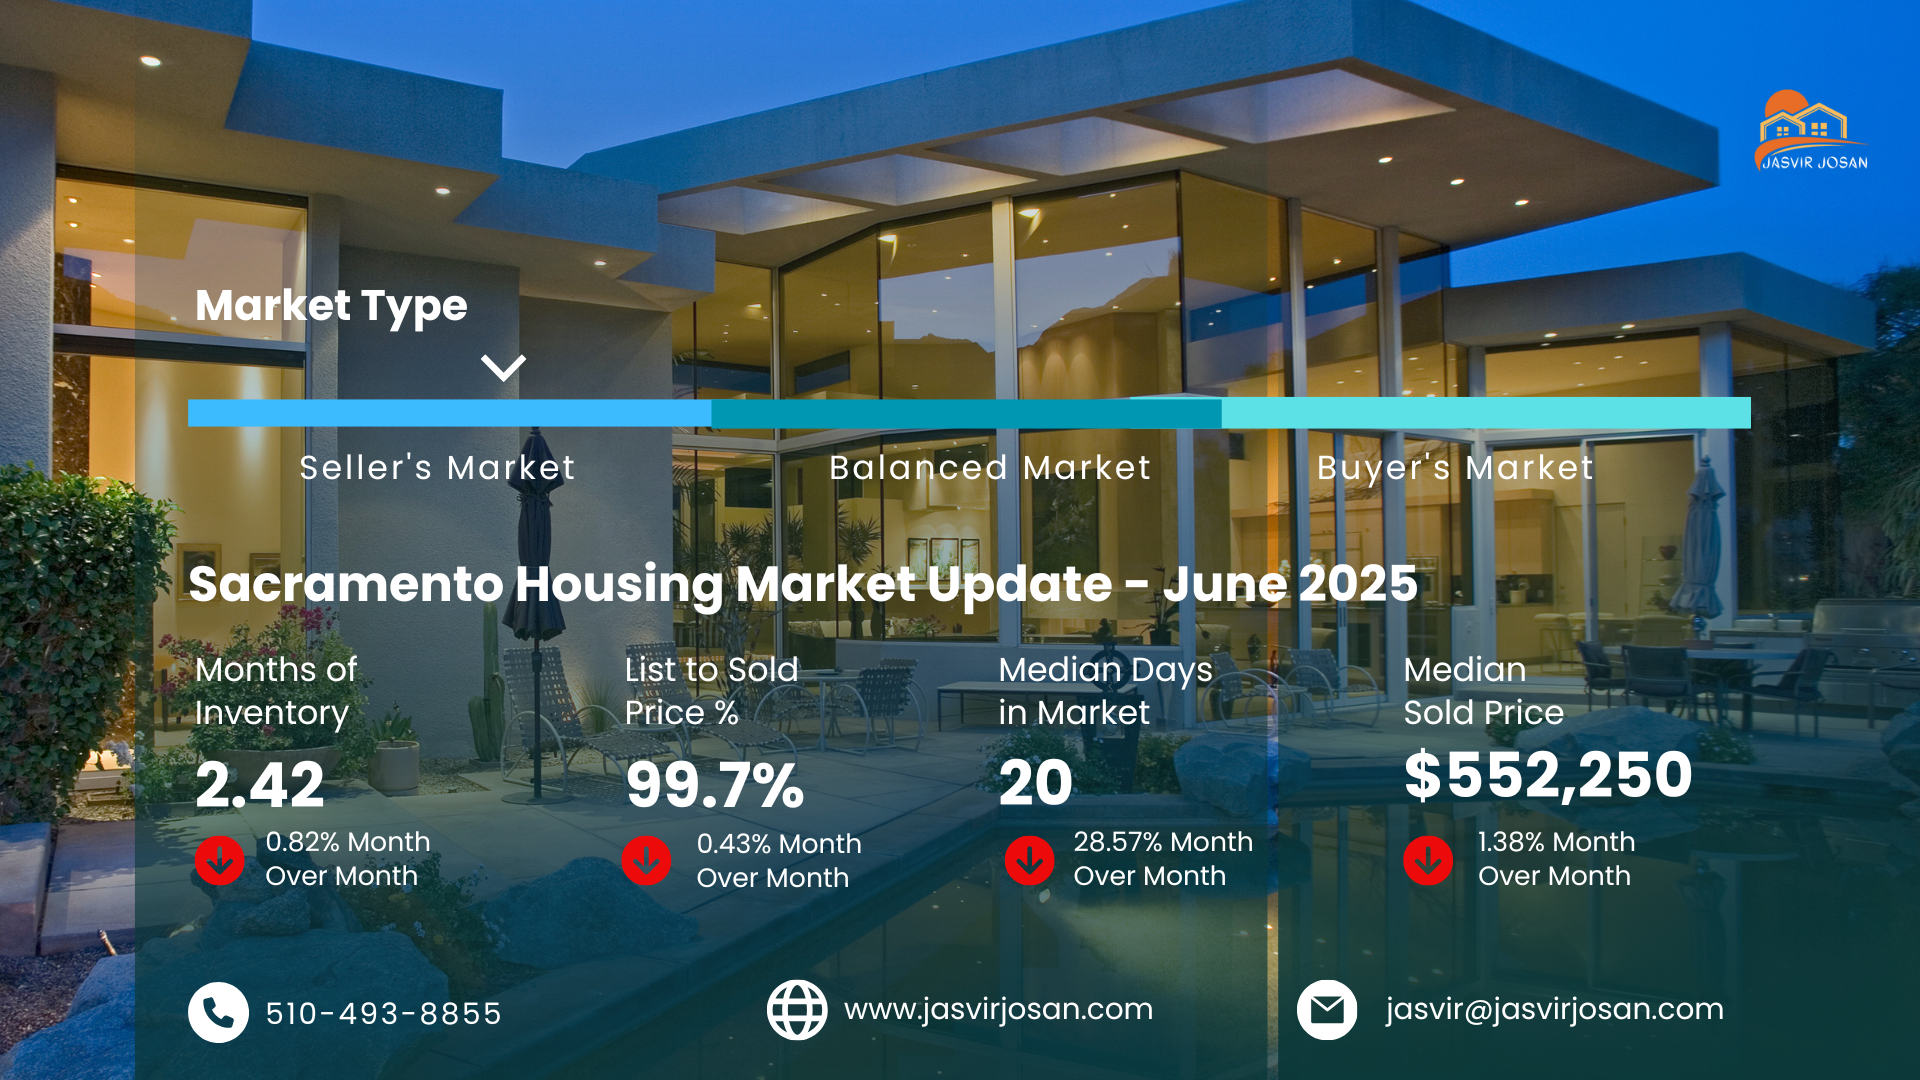
Sacramento Real Estate: June 2025 Market Update – What's Happening Now?

Is the Sacramento real estate market still on fire, or are things cooling down? June 2025 brings some interesting new numbers, and if you're looking for Sacramento homes for sale or thinking about how to sell my home Sacramento, you'll want to read this! We're seeing some shifts, so let's dive into the latest on Sacramento home prices and what it means for you.

June 2025 Sacramento Housing Market: Quick Look

  • Months of Inventory: 2.42 (Slightly Up Month Over Month)
    • What this means: There are a few more homes on the market now compared to last month. This gives buyers a little more choice, but it's still a market where sellers have an advantage.
  • List to Sold Price %: 99.7% (Slightly Down Month Over Month)
    • What this means: Homes are still selling very close to their asking price. This means buyers are still willing to pay what sellers are asking, though it's not quite as high as before.
  • Median Days in Market: 20 (Down 28.57% Month Over Month)
    • What this means: Big news here! Homes are selling much, much faster in June than they were in May. This shows that buyers are jumping on good opportunities quickly.
  • Median Sold Price: $552,250 (Down 1.38% Month Over Month)
    • What this means: The average price homes are selling for has gone down a little bit again. This suggests prices might be settling after a long period of big increases.

What These Numbers Mean For You

  • If You're Buying a Home in Sacramento: The faster selling times mean you need to be ready to act fast when you find a home you like. Get your finances in order and be prepared to make quick decisions. The slight dip in prices might offer a small window for a better deal.
  • If You're Selling Your Home Sacramento: Homes are moving quickly! This is good news for sellers. Make sure your home is priced right and looks its best to attract those fast-moving buyers.

Ready to Make Your Move in Sacramento?

The Sacramento real estate market is always changing. Knowing these numbers helps you make smart choices. Whether you're ready to buy a home in Sacramento or looking to sell a house in Sacramento, I'm here to guide you through every step. Let's chat about your goals!

Posted in Market Updates
July 16, 2025

When To Begin Your Home Search: Your Sacramento Real Estate Timeline

Sacramento neighborhoods, Sacramento housing market forecast, Midtown Sacramento homes, Sacramento real estate market trends, Sacramento real estate agent, Folsom homes for sale, Elk Grove real estate

The thought of discovering your next perfect home, or carefully preparing your current Sacramento property for its next chapter, is incredibly exciting! But once that creative spark ignites, one of the first questions that routinely surfaces is: When should I actually start looking at houses? It is a fantastic question, and the answer isn't a single fixed calendar date. Instead, your ideal start date is a customized blend of personal readiness, intentional financial preparation, and an understanding of our unique local market cycles.

Forget the old narrative that there is a single, identical "perfect" moment that applies uniformly to every buyer. Your ideal starting window is entirely unique to your life. Let's explore the core pillars that determine exactly when it is time to launch your home search in Sacramento.


The Ideal Home Buying Milestone Timeline

To help visualize the entire roadmap, here is how a healthy, stress-free home buying journey generally breaks down chronologically:

Timeline Window Primary Objective Key Action Items
6 to 12 Months Out Financial Foundation & Discovery Audit your credit scores, optimize debt-to-income, and accumulate down payment liquid cash reserves.
3 to 6 Months Out Professional Alignment & Strategy Partner with a local agent, establish neighborhood wishlists, and gather paperwork for mortgage underwriters.
2 to 3 Months Out Formal Approval & Active Touring Secure a formal pre-approval letter, begin private home tours, and actively analyze active market inventory.
1 to 2 Months Out Contract Ratification & Escrow Submit formal offers, complete structural home inspections, finalize loan underwriting, and record your deed.

1. Personal Readiness & Life Milestones

Your lifestyle requirements are the true factor for any real estate transaction. Major life transitions are often the clearest indicators that your housing needs are shifting:

  • Changing Life Dynamics: Milestones such as expanding your immediate family, planning a wedding, or transitioning into an empty-nest phase naturally change your square-footage preferences. Career relocations into the tech and business hubs of Sacramento or a desire to move closer to multi-generational family networks are also massive indicators.
  • Your Current Lease or Sale Cycle: Is your current rental agreement set to expire in the coming months? Do you need to coordinate a simultaneous transaction where you sell your existing Sacramento home before you can safely buy your next one? Correctly organizing these contracts is highly critical.
  • Emotional Alignment: Buying or selling a home is an emotional and energetic journey. Being mentally prepared to tour properties, process contract items, and navigate strategic negotiations is just as important as your financial capacity.

2. Financial Preparation: The Non-Negotiables

For modern homebuyers, preparing your capital layout is an absolute prerequisite that requires advanced planning. This is where your journey technically begins:

  • Down Payment & Closing Capital Reserves: Your down payment allocation can scale anywhere from 3% to 5% for standard conventional paths, up to 20% to avoid private mortgage insurance (PMI), or even 0% down for active-duty military and veterans using VA loans. Crucially, remember to save an additional 2% to 5% of the total loan volume to account for independent escrow closing costs, insurance premiums, and transfer taxes.
  • Credit Health Optimization: Your credit score directly dictates your underlying mortgage interest rate, modifying your monthly payment capacity by hundreds of dollars. Checking your reports early gives you the runway required to pay down credit card balances, eliminate errors, and optimize your scoring profile—a process that easily takes several months.
  • Securing a Formal Pre-Approval Letter: This is a mandatory power move. A true pre-approval letter defines your maximum purchasing power and signals to listing agents that you are a highly qualified buyer whose assets have already passed an initial audit.
📋 Quick-Start Action Tip: Before your first strategy call with a lender, create a digital folder containing your last 30 days of consecutive pay stubs, your trailing two years of W-2 statements, your past two years of federal tax returns, and two months of complete bank statements. This baseline organization accelerates your approval turnaround time immensely.

3. Navigating Sacramento Market Seasonality

While your personal timeline is the ultimate driver, tracking seasonal real estate market shifts across the valley allows you to optimize your purchasing strategy:

  • The Spring & Summer Surge (March–August): This is historically the most active cycle for new homes for sale in Sacramento. High volumes of listings hit the MLS, presenting a broad selection of architectural choices. However, this window also invites maximum buyer competition and multiple-offer scenarios. If choice is your priority, prepare to act decisively.
  • The Autumn & Winter Window (September–February): Market velocity naturally slows down as cooler weather arrives and the holidays approach. While overall inventory contracts, buyer competition drops off significantly. Sellers maintaining active listings during this period are typically highly motivated, giving buyers an excellent climate for price negotiations and seller-paid interest rate buy-downs.
  • Standard Operational Timeframes: Once a purchase contract is formally ratified by both parties, the traditional escrow and loan-processing cycle takes roughly 30 to 45 days to close. Realistically, the full path—from your initial consultation to turning the key in your front door—spans anywhere from 4 to 8 months.

Related: The Pursuit of Home Happiness: Is It Time for a New Address?


Steps You Can Take Right Now (Regardless of Your Moving Date)

Even if your target move-in window is a year or more away, you can establish an immense advantage by following these baseline steps today:

  • Isolate Your Realistic Wishlist: Clearly define your non-negotiable property features versus your flexible "nice-to-have" amenities. Research which distinct regional micro-markets—such as the master-planned neighborhoods of Elk Grove, the scenic hills of Folsom, or the urban tree-lined streets of Midtown Sacramento - align cleanest with your daily lifestyle.
  • Conduct a Thorough Budget Audit: Review your household balance sheet, track recurring debt obligations, and establish an intentional monthly savings target to systematically grow your home buying reserves.
  • Partner with an Experienced Local Agent: Aligning with an expert Sacramento real estate agent early provides you with an objective market resource. An agent acts as your long-term consultant, tracking hyper-local neighborhood patterns and helping you construct a realistic timeline tailored exactly to your lifestyle goals.

Frequently Asked Questions About the Real Estate Timeline

How far in advance should I contact a real estate agent?

The ideal window is 3 to 6 months before you want to physically write an offer on a home. Contacting an agent early allows us to map out a clear strategy, monitor local inventory trends together, and introduce you to premier local mortgage partners well ahead of schedule.

What happens if my current rental lease expires before I find a home?

This is a very common scenario. Your agent can work with you to analyze flexible housing bridges, assist you in negotiating a month-to-month lease extension with your current landlord, or structure an intentional escrow timeline with a seller to keep your move-in dates seamless.


Your Journey Accelerates When You Are Ready

At the end of the day, successfully launching a home search across the Sacramento landscape isn't about stress-testing or perfectly predicting macro-economic market windows. It is about matching your individual life readiness with careful financial planning. When those pieces lock into place, you have your official green light to move forward.

Ready to construct your custom Sacramento home buying timeline? Whether you are planning a first-time purchase, coordinating a complex property upgrade, or simply curious about local micro-markets, let's collaborate. Contact our office today for a private, no-obligation strategy consultation, and let's map out your ultimate path to homeownership!

Posted in Buyer Tips
July 9, 2025

The Pursuit of Home Happiness: Is It Time for a New Address?

Evaluating whether it is time to buy a new home or sell your current property in Sacramento

There is something undeniably exciting about the prospect of a new beginning—a fresh start in a physical space that perfectly aligns with exactly who you are and where you stand in life today. Perhaps you have found yourself mindlessly scrolling through property portals late at night, or maybe you are simply feeling that subtle, persistent nudge telling you your current layout no longer serves your daily routine. Whatever ignited that initial spark, a fundamental question naturally emerges: Is a new home officially on your lifestyle wishlist?

For countless homeowners and aspiring buyers across the Greater Sacramento region, the answer is a resounding yes. Whether you are craving more square footage to expand, seeking to eliminate weekend yard maintenance, targeting a new school zone, or looking for a blank canvas to customize, the pursuit of residential happiness is a powerful motivator. Let’s explore what drives that homeownership dream and how you can seamlessly transform your wishlist into reality in our dynamic local market.


The Property Audit: Is Your Current Home Still the Right Fit?

Before touring model homes, take a moment to evaluate your current living arrangements against this quick-reference lifestyle matrix:

Current Home Symptom The Underlying Need The Ultimate Sacramento Solution
Cramped rooms, shared kids' bedrooms, zero storage Upsizing & structural expansion Targeting master-planned neighborhoods with 4+ bedroom layouts.
Empty bedrooms, exhausting yard work, high utility bills Downsizing & lifestyle optimization Transitioning to low-maintenance single-story homes or luxury townhomes.
Long commutes, car-dependent errands, quiet streets Vibrant urban or suburban vibe shift Relocating to highly walkable historic corridors or active suburban pockets.
Outdated kitchens, no office, poor energy performance Modern architectural amenities Exploring smart-home integrated custom builds or newer builds.

Why a New Home is Calling Your Name

The trigger that prompt a move are deeply personal, yet distinct patterns consistently surface for buyers and sellers throughout Sacramento:

For Aspiring and Moving Buyers:

  • The Need for Upgraded Space: A floor plan that performed beautifully five years ago can easily become crowded as your family grows. If you find yourself needing additional bedrooms, a larger perimeter yard, or dedicated zones for remote learning, it is time to explore upscale upsizing strategies.
  • The Empty Nest Transition: Once children move on to their own independent chapters, managing extra unutilized rooms and demanding landscaping schedules can feel like an unnecessary chore. Switching focus to a refined, low-maintenance single-story property allows you to reclaim your weekends.
  • Neighborhood Energy Matching: Your surroundings dictate your lifestyle. You might be searching for a highly walkable urban community, a tranquil cul-de-sac, or premier suburban enclaves known for top-tier school systems.
  • Trading Rent Receipts for Real Equity: For current tenants, the desire to escape landlord restrictions, stabilize housing costs, and build personal wealth is an incredibly strong motivator to secure that foundational first property.
  • Targeted Work-From-Home Features: Modern floor plans cater directly to today's lifestyles, featuring dedicated, quiet home offices, modern tech stations, and seamless indoor-outdoor living integration.

Related: Navigating the Home Buying Process: Tips for First-Time Buyers

For Sellers Preparing to Make a Move:

  • Capitalizing on Accumulated Wealth: Homeowners across the region have built substantial, long-term equity. Selling your current property allows you to unlock that net worth and deploy it as a massive down payment toward a custom brand-new build.
  • Financial Streamlining: Scaling down into a highly efficient property can instantly free up investment capital, slash your monthly overhead, and simplify your broader financial footprint.

Mapping Out Your Perfect Home Parameters

Every buyer’s definition of a perfect home is unique. As you map out your next move, consider which elements are your non-negotiables:

  • Geographic Location: Are you prioritizing a specific neighborhood, or do you prefer the sprawling suburban landscape? Do you see yourself putting down roots in the master-planned communities of Roseville, the peaceful neighborhoods of Citrus Heights, or the fast-growing corridors of Rancho Cordova?
  • Outdoor Living Design: Do you require an expansive yard for hosting gatherings, a simple low-maintenance patio, or a custom backyard swimming pool to beat the summer heat?
  • Eco-Friendly Features: Moving into a home equipped with advanced insulation packages, integrated solar panel systems, and energy-efficient windows can dramatically lower your monthly utility costs.
💡 The Market Reality Check: The local real estate landscape moves quickly. For buyers, setting a firm financial foundation through early mortgage pre-approval is mandatory to remain competitive. For sellers, obtaining an objective asset valuation is the essential first step to understanding exactly how much purchasing power you can carry forward into your next purchase.

Frequently Asked Questions About Upgrading Your Address

Should I sell my current Sacramento home before buying a new one?

This depends entirely on your financial situation and comfort level. Selling first provides you with liquid cash and eliminates the need for a home sale contingency in your next offer. However, if you prefer a seamless transition, we can explore structuring a concurrent escrow or utilizing specialized bridge financing to let you buy before you sell.

How do I determine what my current home is worth in today's market?

Online automated estimators only look at basic public records. To find the true market value of your property, your agent will conduct an in-depth comparative market analysis, factoring in recent hyper-local neighborhood sales, current inventory supply, and your home's unique upgrades.


Let's Translate Your Wishlist Into a Reality

Your dream property shouldn't live permanently on a wish list—it is a concrete milestone waiting to be unlocked. By clearly defining your lifestyle priorities, auditing your financial position, and aligning with an experienced local guide, you can navigate your next transition with absolute confidence.

Is it officially time to turn the page to your next residential chapter? Let’s collaborate to make it happen. Connect with our team today for a private, data-driven strategy session. Whether you want to maximize your current equity or dive into a customized property search, we are here to protect your interests every step of the way!

Posted in Buyer Tips
July 2, 2025

Stop Trying To Time The Market: Your Best Move is Always Now

Stop trying to time the Sacramento real estate market and focus on personal readiness

We have all heard the familiar whispers at dinner parties and water coolers, haven't we? "Wait for prices to drop." "Hold off until interest rates hit the floor." "The market is going to crash, just hold onto your cash!" The temptation to strategically "time the market"—to buy a home at the absolute lowest point or sell at the ultimate peak—is incredibly strong, especially in a dynamic region like Sacramento.

But here is a candid truth bomb from your local real estate expert: trying to perfectly time the real estate market is almost always a losing game.

Why? Because the "perfect" moment is exclusively visible in hindsight. Let's dive into why abandoning market predictions and focusing entirely on your personal financial goals is the smartest possible move for both buyers and sellers.


The Mathematical Illusion of "Perfect Timing"

Real estate markets are complex ecosystems. They are influenced by a long list of unpredictable factors: mortgage interest rates, local job growth, inflation data, and even global trade events. Predicting how all these elements will converge to create a precise peak or valley is virtually impossible.

  • You Are Competing Against Hindsight: When you decide to wait for a supposed "dip," you are competing against thousands of other sidelined buyers who have the exact same idea. Once the market shifts, collective buyer action instantly drives prices right back up, making that anticipated "perfect moment" vanish before you can write an offer.
  • The Hidden Cost of Waiting: While you wait for a potential dip in asking prices, other financial factors are constantly moving. A slight increase in interest rates can easily wipe out the savings of a lower purchase price.

The Cost of Waiting: A Real-World Example

To prove why waiting for a price drop often backfires, look at how a minor 0.5% increase in mortgage rates completely erases a $25,000 price reduction on a standard Sacramento home (assuming a 20% down payment):

Scenario Home Price Interest Rate Monthly Payment (P&I)
Buying Now $525,000 6.0% $2,518 / month
Waiting for a Price Drop $500,000 (A $25k savings!) 6.5% (Rates ticked up) $2,528 / month

*Result: You waited months to "save" $25,000, but you actually ended up with a higher monthly payment!


Why Timing the Market Backfires for Buyers

  • Interest Rate Volatility: As shown above, a lower purchase price is instantly neutralized by higher borrowing costs. A higher rate dictates a larger monthly payment, ultimately costing you tens of thousands of dollars more over the life of a 30-year loan.
  • Surging Competition: When prices do artificially drop (or rates temporarily dip), the market is flooded with competing buyers. You will likely find yourself in stressful bidding wars, forcing you to waive contingencies or compromise on the features you truly want.
  • Sacrificing Long-Term Appreciation: Historically, real estate appreciates steadily over time. By sitting on the sidelines for two years waiting for a crash, you miss out on two years of wealth-building equity.

Why Timing the Market Backfires for Sellers

  • Chasing the Peak: You might reject a strong, fair offer today holding out for a "record-breaking" price tomorrow. If market sentiment shifts, you could experience longer listing times and ultimately be forced into aggressive price reductions.
  • The Paralysis of Opportunity Cost: While your home sits idle waiting for perfect economic conditions, you are putting your actual life on hold. You miss out on relocating, downsizing seamlessly, or securing your next dream property.
  • Bleeding Carrying Costs: Every extra month you wait to list your property, you are paying property taxes, insurance premiums, maintenance, and mortgage interest. These "carrying costs" silently eat into the extra profit you were hoping to capture.
💡 The Expert Rule of Thumb: "Time in the market will always beat timing the market." Real estate is a long-term hold, not a day-trading asset.

Focus on Your Personal Goals, Not the News Cycle

Instead of trying to outsmart large economic trends, shift your focus entirely to what you can control: your personal financial foundation and your family's lifestyle goals.

For Buyers:

  • Financial Readiness: Are your core finances organized? Do you have your down payment properly saved? Get pre-approved by a trusted local lender so you know your exact buying power today.
  • Your Life Stage: Are you expanding your family, or are you simply exhausted by annual rent increases? Your internal biological and professional timing is infinitely more important than external market timing.
  • The 5-Year Horizon: If you plan to live in the home for at least 5 to 7 years, short-term market fluctuations do not matter. This runway allows you to effortlessly ride out market cycles while paying down principal and building home equity.

For Sellers:

  • Lifestyle Drivers: Are you relocating for a career, moving closer to grandchildren, or liquidating an investment? Let these profound personal drivers dictate your listing date.
  • Property Preparation: Focus on presenting a flawless product. A meticulously maintained and beautifully staged property will always command top dollar and perform exceptionally well, regardless of whether the broader market is up or down.

Frequently Asked Questions

If I buy now and the market dips next year, did I make a mistake?

No. Your home is a place to live, not just a stock ticker. As long as you secured a fixed-rate mortgage you can comfortably afford, a temporary dip in paper value does not impact your daily life or your monthly payment. Historically, values recover and climb higher over a standard 7-to-10-year holding period.

Should I wait for interest rates to drop before I buy?

If you find a home you love and can afford the payment today, buy it. If rates drop significantly in the future, you can always refinance to lower your payment. If you wait, you risk home prices appreciating further, locking you out of the neighborhood entirely.


Your Best Move is Always Now (When YOU Are Ready!)

The real estate market will always have its natural ebbs and flows. The most successful homeowners are those who enter the market when it aligns precisely with their life goals and financial stability.

Ready to mute the noise and make a confident move in the Sacramento area? Whether you are preparing to buy or sell, let's sit down, review your unique situation, and build a data-driven strategy that puts your needs first—not a crystal ball. Contact us today for a personal, no-obligation consultation!

June 26, 2025

Is It Time to Think About Downsizing Your Home?

empty nest home, reduce home maintenance, simplify living home, Sacramento bungalows for sale, sell house move smaller

Our homes are more than just buildings; they're canvases for our lives, evolving right alongside us. What once perfectly fit a growing family might now feel a bit… too big. Or perhaps you're simply tired of endless upkeep, or eyeing a more financially flexible future. If thoughts of a smaller, more manageable living space have crossed your mind, you're not alone! Many Sacramento homeowners are asking themselves: "Is it time to think about downsizing?"

It's a big question, often with significant financial and lifestyle implications. Let's explore why downsizing might just be your next smart move, whether you're selling a larger property or considering a cozier new home in our wonderful Sacramento area.

What Exactly Does "Downsizing" Mean?

Downsizing isn't just about moving into a "smaller" house. It's about optimizing your living space to better suit your current needs, budget, and lifestyle. It could mean trading a sprawling family home for a charming bungalow, a spacious suburban house for a vibrant downtown condo, or even a large yard for a low-maintenance patio home in an active adult community. It’s about more intentional living!

Why Consider Downsizing? The Benefits are Real!

People choose to downsize for a variety of compelling reasons, often finding a newfound sense of freedom and ease.

  • Financial Freedom & Savings: This is often a huge motivator!
    • Lower Mortgage Payments (or None!): Selling a larger, highly appreciated home could mean buying a smaller one outright, or at least significantly reducing your monthly mortgage. Imagine that!
    • Reduced Property Taxes & Insurance: A less expensive home generally means lower annual property tax bills and more affordable homeowner's insurance premiums.
    • Cheaper Utilities: Heating and cooling a smaller space, especially during our Sacramento summers, uses far less energy, leading to noticeably lower utility bills.
    • Released Equity: For many long-time homeowners, downsizing allows them to tap into years of built-up home equity, creating a fantastic nest egg for retirement, travel, or other financial goals.
  • Less Maintenance & Upkeep: Are you tired of constant cleaning, extensive yard work, or never-ending repairs?
    • A smaller home means less square footage to clean and fewer rooms to maintain.
    • Smaller yards, or even no yards (in a condo or townhome), mean saying goodbye to weekend chores and hello to more free time. Think about it: no more mowing or endless leaf blowing!
  • Simplified Living & Decluttering: This can be incredibly liberating.
    • Downsizing forces you to evaluate your possessions, keeping only what truly brings you joy or is essential. It's a wonderful opportunity for a fresh start!
    • Less stuff means less clutter, leading to a more organized and stress-free living environment.
  • Lifestyle Shift: Your needs change, and your home can too!
    • Empty Nesters: When the kids move out, those extra bedrooms can feel like wasted space. Downsizing can free you from maintaining rooms you no longer use.
    • Retirement & Travel: With fewer home responsibilities and potentially more cash, you can spend your golden years pursuing hobbies, traveling the world, or enjoying our amazing local attractions without worry.
    • Increased Convenience: Perhaps you want to be closer to family, or closer to downtown Sacramento's vibrant scene, or enjoy amenities like a community pool without the private upkeep.
  • Environmental Impact: A smaller footprint often means a more eco-friendly lifestyle, using fewer resources for heating, cooling, and maintenance.

Is Sacramento a Good Place to Downsize? Absolutely!

The Sacramento real estate market offers a diverse range of options for those looking to downsize. We have charming bungalows in established neighborhoods, modern condos and townhomes closer to the city center, and fantastic active adult communities (55+ communities) in areas like Roseville and Elk Grove that are specifically designed for low-maintenance, amenity-rich living. With varied pricing and home styles, finding your perfect smaller fit in Sacramento is highly possible!

What to Consider Before You Make the Leap:

While the benefits are plentiful, downsizing is a big decision that requires careful thought.

  • Emotional Attachment: It's natural to have deep emotional ties to a home where you've created countless memories. Take time to process this.
  • Space for Hobbies & Guests: Will your new, smaller space still accommodate your hobbies, crafts, or visits from family and friends? Consider clever storage solutions!
  • New Neighborhood & Community: Moving means a new environment. Research neighborhoods that align with your desired lifestyle – walkable areas, quiet streets, or communities with specific amenities.
  • The Cost of Moving: Remember to factor in potential costs like closing costs on both ends, and professional moving services. These can add up!

Ready to Explore Your Downsizing Options in Sacramento?

Deciding to downsize is a personal journey, but you don't have to navigate it alone. If you're thinking about selling your current Sacramento home and finding a new, more suitable space, I'm here to help. Let's discuss your goals, explore the Sacramento housing market options, and create a personalized plan to make your transition smooth and successful.

Contact us today for a personalized, no-obligation consultation! Let's talk about how downsizing could open up exciting new possibilities for your life.

Posted in Homeowner Tips